The Complete Guide to Business Exit Readiness & Valuation
Selling a business is the most significant financial transaction most owners will ever make. The proceeds fund retirement, family legacy, the next venture, or simply the freedom to do something different. And yet most business owners spend more time planning a vacation than planning their exit.
The result is predictable: businesses that sit on the market too long, sell below their potential, or fall apart in due diligence when problems surface that could have been addressed years earlier. Sellers who feel blindsided by deal structures they didn’t understand, tax bills they didn’t anticipate, or closing amounts that were dramatically lower than the headline number suggested.
This guide exists to change that.
What follows is the most comprehensive resource we know of on business exit readiness and valuation — built specifically for business owners who want to understand the full landscape before they make decisions, brokers and M&A advisors who serve those owners, and CPAs and exit planners who help clients navigate the most complex financial event of their business lives.
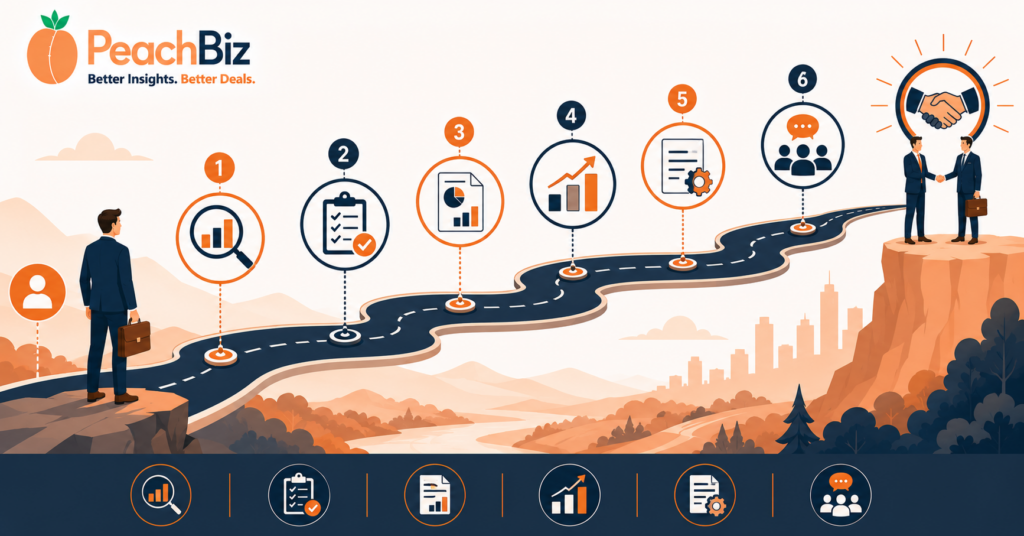
We’ve organized it into six topic clusters, each covering a critical dimension of the exit process. Every section gives you the essential concepts and links to our in-depth articles where you can go deeper on any topic that’s most relevant to your situation.
Start at the beginning if you’re new to exit planning. Jump to the section most relevant to where you are if you’re already in process. Use it as a reference whenever a specific question comes up.
This is the guide we wish every business owner had read two years before they decided to sell.
How to Use This Guide
This guide is organized into six clusters that follow the natural sequence of an exit:
- Understanding Valuation Fundamentals — What your business is worth and how that number is calculated
- Exit Readiness — How buyers evaluate your business and what “ready to sell” actually means
- Financial Documentation — The financial presentation that either earns your asking price or costs it
- Value Drivers and Value Killers — The specific factors that move your multiple up or down
- Deal Structure — How the terms of your deal determine what you actually walk away with
- Advisor Strategy — How to build the professional team and relationships that make exits work
Each cluster summary links to the full in-depth articles for readers who want to go deeper. The free tools referenced throughout give you a way to apply the concepts to your own specific numbers.
Part 1: Understanding Valuation Fundamentals
The starting point for every exit is understanding what your business is actually worth — not what you hope it’s worth, not what a friend said their business sold for, but the number a qualified buyer using standard methodology would pay under current market conditions.
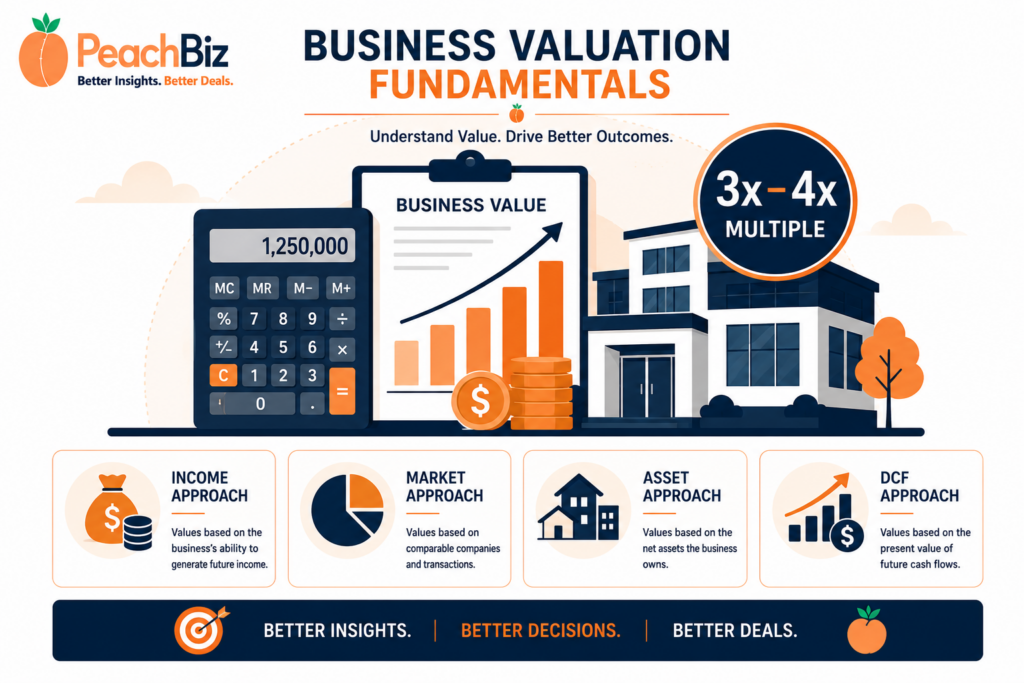
The four valuation methods form the foundation of this understanding. Income-based approaches (using SDE multiples for smaller businesses and EBITDA multiples for larger ones) are the most common for operating businesses. Market-based approaches validate those numbers against comparable closed transactions. Asset-based approaches establish the floor. Discounted cash flow models project future performance for growth-oriented deals. Most transactions use a combination — with income as the anchor and market comps as the validation.
Industry multiples are real, measurable, and significantly more variable than most sellers realize. The difference between a business at the low end of its industry range and one at the top can be 100% or more in total enterprise value — on identical earnings. Understanding where your business falls within its range, and why, is the prerequisite to knowing whether your asking price is defensible.
The gap between asking price and market value is one of the most consistent sources of failed transactions. Sellers anchor on what they need or what they’ve invested. Buyers calculate what the business earns and what comparable businesses have sold for. Those two frameworks produce different numbers — and the gap between them is where most deals die before they begin.
Enterprise value and equity value are not the same number — and confusing them is one of the most expensive mistakes a seller can make. Enterprise value is what the buyer agrees to pay. Equity value is what you actually receive after debt payoffs, working capital adjustments, transaction costs, and deal structure effects. Understanding the waterfall from enterprise value to closing proceeds is essential before you evaluate any offer.
Go deeper on valuation fundamentals:
- What Is a Business Worth? The 4 Valuation Methods Explained
- EBITDA Multiples by Industry: What Buyers Are Actually Paying Right Now
- Why Your Asking Price and Your Business Value Are Two Different Numbers
- The Difference Between Enterprise Value and Equity Value (And Why It Matters at Closing)
👉 Get your baseline valuation now with our free Business Valuation Calculator — built on real transaction data, no email required.
Part 2: Exit Readiness
Knowing your business’s value is the starting point. Knowing whether it’s actually ready to sell — whether it will hold up to a buyer’s scrutiny, attract qualified offers, and close without drama — is a different and equally important question.
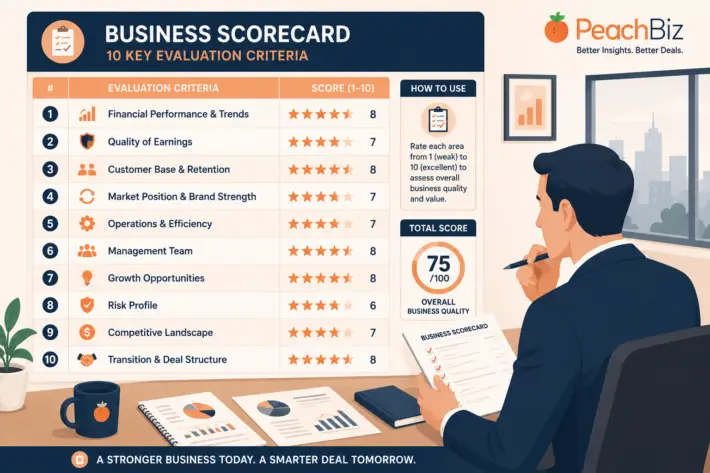
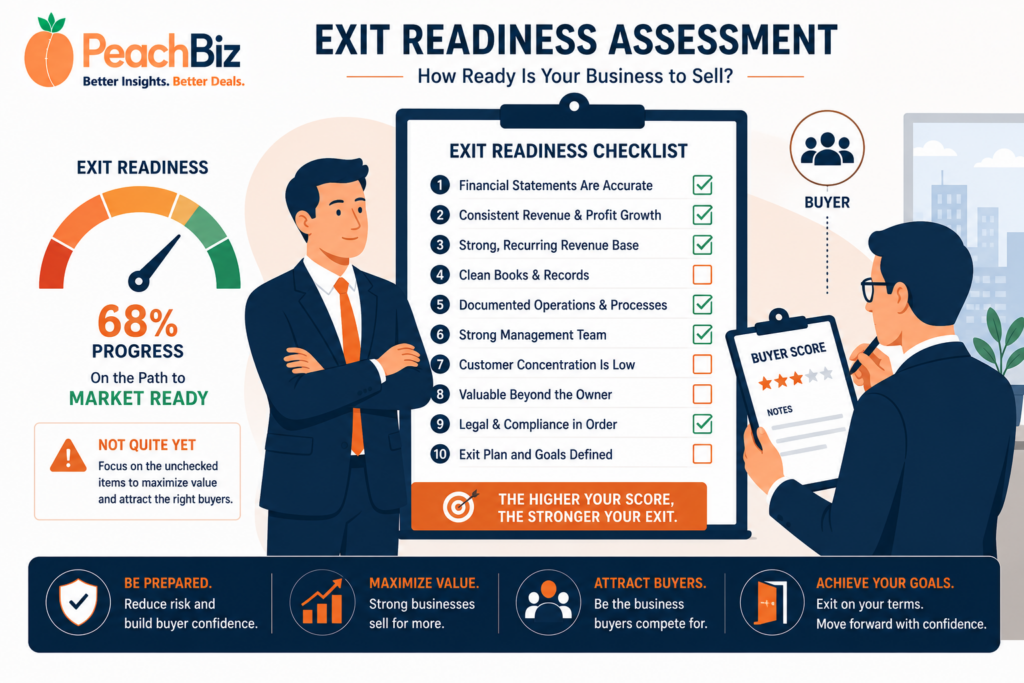
Buyers score your business before they make an offer. There are ten specific factors they evaluate — revenue trend, earnings quality, customer concentration, owner dependence, recurring revenue, documented systems, management team depth, market position, growth potential, and legal/compliance history. Understanding these factors before a buyer does gives you the opportunity to address weaknesses rather than be surprised by them.
An exit readiness assessment is the structured diagnostic that tells you where you stand on each of these dimensions and what to do about it. Done 18–36 months before your target sale date, it gives you enough runway to act on the findings. Done at the right time, with the right professional guidance, it’s one of the highest-ROI activities available to any business owner planning an exit.
Red flags kill deals before the LOI — often before the seller even knows a buyer was evaluating them. The most common deal-killers aren’t discovered in due diligence; they surface in the first 30 days of buyer evaluation and trigger a quiet withdrawal. Finding these issues yourself — before a buyer does — and addressing or disclosing them proactively is the difference between a failed listing and a successful sale.
“Deal-ready” has a specific definition that most sellers don’t know until they’re trying to achieve it under time pressure. It means clean three-year financials, a business that passes the bus test operationally, no single customer representing a critical revenue risk, clean legal and compliance standing, and a documented transition plan. Getting there takes longer than most sellers expect — and the time to start is well before the date you want to close.
Go deeper on exit readiness:
- The 10 Factors Buyers Score Before They Make an Offer
- How to Run an Exit Readiness Assessment on Your Client’s Business
- Red Flags That Kill Deals Before the LOI: A Pre-Sale Checklist
- What “Deal-Ready” Actually Looks Like — And How Long It Takes to Get There
Part 3: Financial Documentation
The financial presentation you bring to market is the foundation of your valuation — and the thing that either earns buyer trust or destroys it. The most common reason businesses sell below their potential isn’t a weak market or a difficult buyer. It’s a financial presentation that can’t be verified, that contains add-backs buyers won’t accept, or that tells a different story than the tax returns and bank statements support.
EBITDA add-backs are where sellers most commonly either leave money on the table or create credibility problems. Legitimate add-backs — owner compensation, depreciation, interest, documented one-time expenses — can significantly increase your normalized earnings when presented correctly. Aggressive or indefensible add-backs — unreported cash, recurring expenses labeled as one-time, projected revenue — trigger skepticism that contaminates every other number in your presentation.
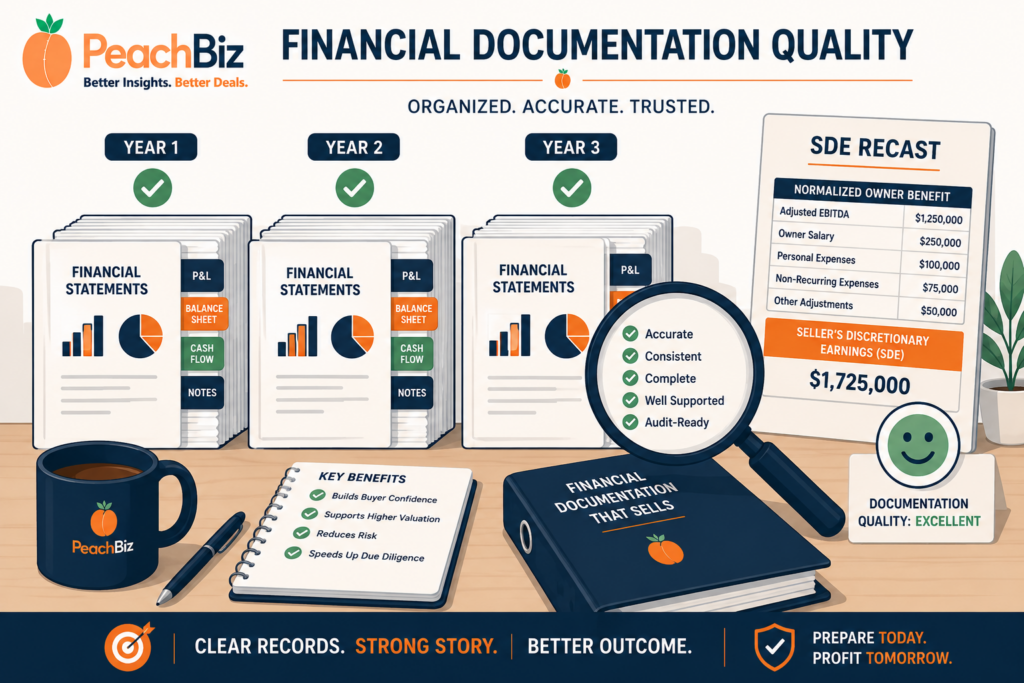
The SDE statement is the most important financial document in your business sale. Built correctly — starting from the tax return, documenting every add-back with source documents, running three years side by side — it’s the foundation of a credible valuation. Built incorrectly, it’s the liability that unwinds your deal in due diligence.
Buyers read three years of financials like detectives — not looking for what’s there, but looking for what’s inconsistent, unexplained, or doesn’t reconcile. Understanding how they read your financials — what they focus on first, what they cross-reference, what triggers concern — gives you the ability to present your numbers in a way that builds confidence rather than raising questions.
Clean books are worth more than a higher multiple. This is the counterintuitive truth that changes how the most sophisticated sellers approach pre-sale preparation. The multiple is largely set by the market. Clean, verifiable, reconciled financial records are entirely within your control — and their impact on actual sale proceeds, through reduced documentation discounts, faster due diligence, SBA lender acceptance, and smaller escrow holdbacks, exceeds what most sellers realize.
Go deeper on financial documentation:
- The EBITDA Add-Backs Buyers Accept vs. The Ones That Blow Up Deals
- How to Build a Seller’s Discretionary Earnings (SDE) Statement That Holds Up Under Due Diligence
- 3 Years of Financials: What Buyers Read, What They Ignore, and What Scares Them
- Why Clean Books Are Worth More Than a Higher Multiple
Part 4: Value Drivers and Value Killers
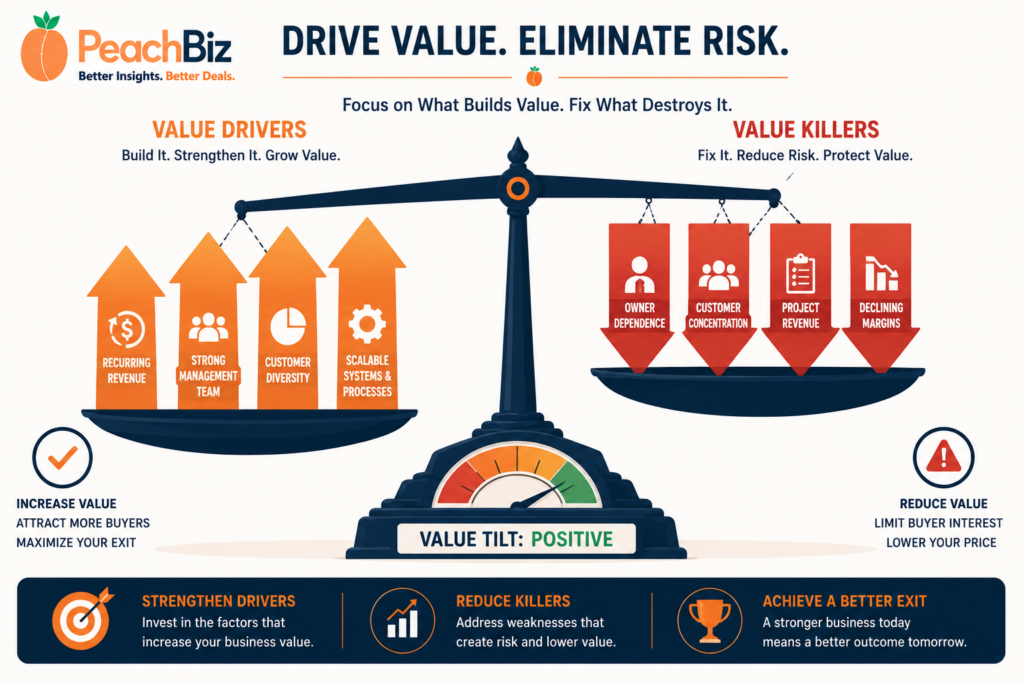
Your multiple isn’t fixed by your industry. It’s set by your business — by the specific, measurable characteristics that buyers recognize and consistently pay more or less for. Understanding what moves multiples up and what moves them down is where the most actionable value creation work happens.
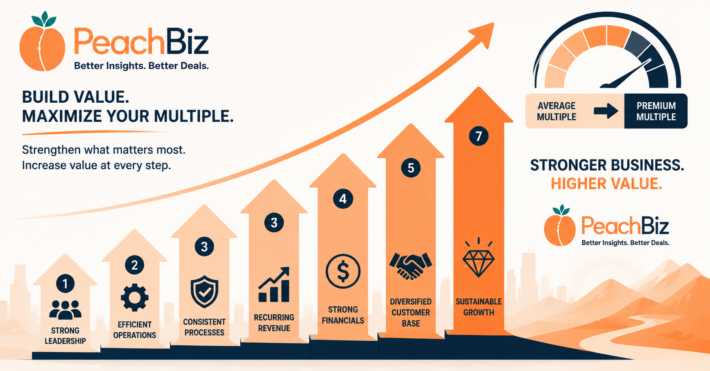
Seven value drivers consistently push multiples toward the top of industry ranges: recurring revenue, management team depth, customer diversification, documented systems, clean financial history, demonstrated growth trajectory, and transferable competitive advantage. Building even two or three of these deliberately — over a 24–36 month runway before a sale — can shift your multiple by 1.0x–2.0x, which at meaningful earnings levels represents hundreds of thousands or millions of dollars.
Owner dependency is the single most common value killer in small business sales — and the one most sellers are most blind to about their own companies. When a business needs the owner to function, buyers price in the transition risk. The result is a lower multiple, a smaller buyer pool, and deal structures that shift post-closing risk onto the seller. Reducing owner dependence before going to market is one of the highest-ROI activities available to any business owner — but it takes 18–24 months of consistent effort to produce evidence that buyers trust.
Customer concentration is the other most common deal-killer — and like owner dependence, it’s most damaging when sellers have underestimated it. A single customer representing 30%+ of revenue can compress your multiple by 0.5x–1.5x, restrict SBA financing, and require earnout provisions that transfer post-closing revenue risk onto you. The fix is diversification — systematic and started early enough to actually change the concentration ratios buyers see in your three-year financial history.
Recurring revenue vs. project revenue is the sharpest multiple lever available in most industries. Businesses with 60%+ recurring revenue consistently trade at 1.0x–2.0x above comparable businesses with primarily transactional revenue — on identical earnings. Converting even a portion of your revenue to a recurring structure in the years before a sale is one of the most direct paths to a meaningfully higher valuation.
Go deeper on value drivers and value killers:
- The 7 Value Drivers That Push Your Multiple Above the Midpoint
- Owner Dependency: The Single Biggest Value Killer in Small Business Sales
- How Customer Concentration Tanks a Valuation (And How to Fix It Before You Sell)
- Recurring Revenue vs. Project Revenue: How Buyer Perception Changes the Math
👉 See how specific improvements would affect your valuation with our free EBITDA Growth Calculator.
Part 5: Deal Structure
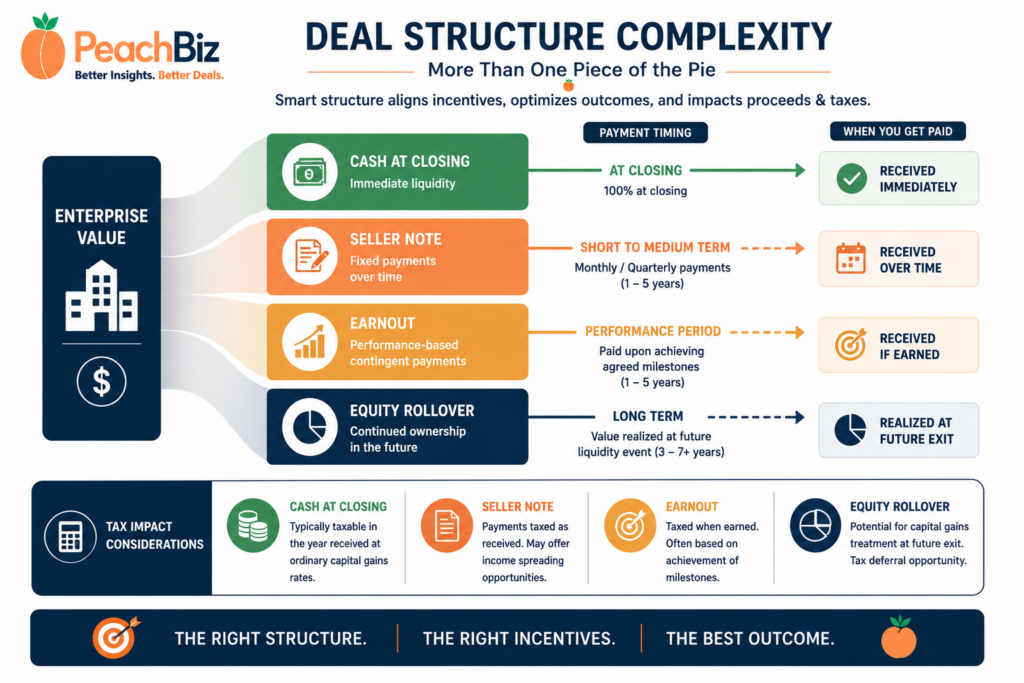
The enterprise value on your LOI is where the negotiation starts — not what you actually receive. Deal structure is the mechanism through which that number gets converted into actual proceeds, and it’s where buyers exercise the most sophisticated leverage in any transaction.
The four components of deal structure — cash at closing, seller notes, earnouts, and equity rollovers — each have different implications for the timing, certainty, and risk allocation of your proceeds. Cash at closing is certain. Seller notes are deferred but relatively predictable. Earnouts are contingent on post-closing performance that you no longer control. Equity rollovers are at-risk investments in the buyer’s future success. Understanding each component before you evaluate any offer is essential for negotiating from an informed position.
Earnouts are the most complex and most contentious component of deal structure — a mechanism that can legitimately bridge a valuation gap or shift all the risk of uncertain future performance onto a seller who’s already handed over the keys. Knowing when earnouts make legitimate sense, when they’re a red flag, and how to protect yourself when you have to accept one is some of the most valuable knowledge you can bring to deal negotiations.
Seller financing, used strategically, can actually increase your sale price rather than reduce it — by expanding your buyer pool, creating competitive pressure that supports a higher enterprise value, and signaling confidence that justifies a premium. The sellers who use it most effectively treat it as a feature rather than a concession, and structure it carefully to protect their interests.
Asset sale vs. stock sale is the tax decision that most sellers don’t understand until it’s too late to optimize — and it can shift after-tax proceeds by six figures on a mid-market transaction. The buyer’s preferred structure (almost always an asset sale) and the seller’s preferred structure (almost always a stock sale) diverge for legitimate reasons that both parties need to understand before they negotiate.
Go deeper on deal structure:
- How Deal Structure Affects the Real Price You Walk Away With
- Earnouts: When They Make Sense and When They’re a Red Flag
- Seller Financing as a Value Lever: How It Can Increase Your Sale Price
- Asset Sale vs. Stock Sale: The Tax Impact Nobody Talks About Early Enough
👉 Model different deal structure scenarios with our free Business Financing Calculator.
Part 6: Advisor Strategy
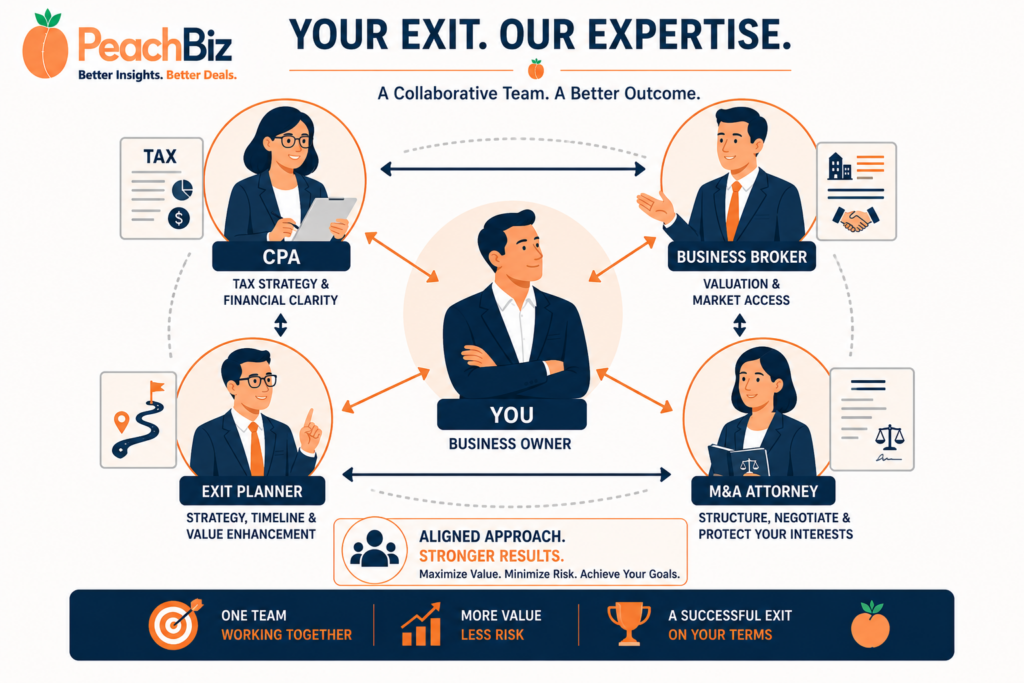
No business owner navigates a successful exit alone. The quality of your advisory team — and how well they work together — is one of the most significant determinants of your outcome. Understanding each advisor’s role, when to engage them, and how to build a coordinated team is as important as understanding valuation or deal structure.
CPAs are often the first call when a business owner begins thinking about an exit — and they’re uniquely positioned to add value before any other advisor is engaged. The CPA who understands M&A can shape entity structure decisions years in advance, model the after-tax impact of different sale structures, prepare the financial documentation that supports a credible valuation, and serve as a knowledgeable partner through every stage of the transaction. The CPA who doesn’t know what they don’t know in this area can inadvertently create problems that cost their client significantly.
Exit planners and business brokers serve different but complementary functions — and the friction between them when roles aren’t clear creates real costs for mutual clients. Exit planners build the business worth selling; brokers sell it. The best exits happen when both disciplines are engaged in the right sequence, with clear role boundaries, and with a collaborative relationship established before a shared client appears.
The referral engine is the infrastructure that the most successful advisors in the exit planning space build deliberately — a network of complementary professionals who refer clients to each other consistently, collaborate on shared engagements, and collectively serve business owners better than any single advisor could. Building this network takes time and intentionality, but it’s the most efficient and most sustainable source of ideal clients available to any advisor in this space.
Go deeper on advisor strategy:
- What CPAs Need to Know Before Their Client Decides to Sell
- How Exit Planners and Business Brokers Can Work Together (Without Stepping on Each Other)
- Building an Exit Planning Practice: The Referral Engine Between Advisors
The Exit Readiness Timeline: Where You Are and What to Do Next
Understanding the full landscape is most useful when it connects to action. Here’s how to use this guide based on where you are in your timeline.
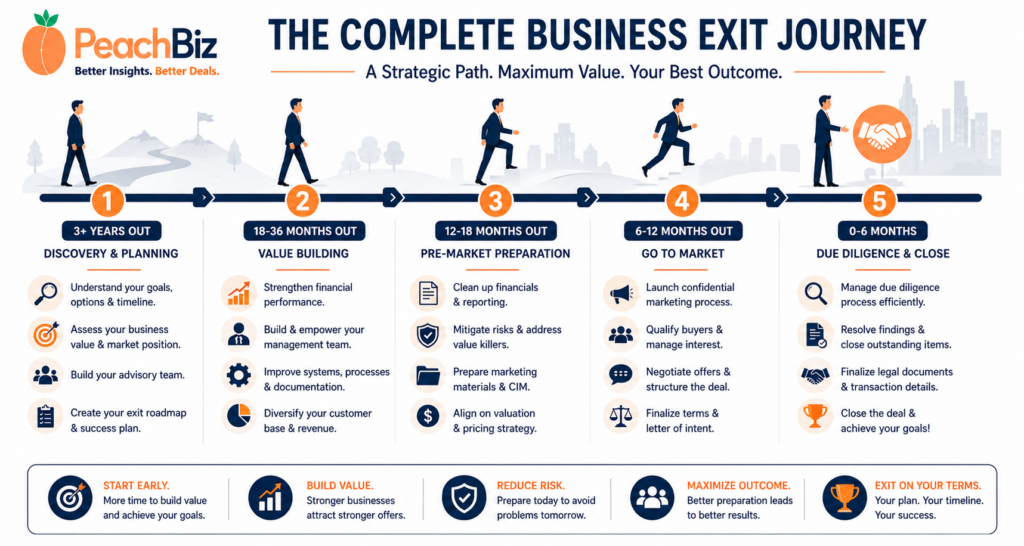
3+ Years Before Your Target Sale
You have the most valuable resource available: time. This is the window for the highest-ROI work — entity structure optimization, recurring revenue development, owner dependence reduction, customer diversification, and financial documentation cleanup. None of these happen quickly, which is exactly why starting now matters.
Priority actions:
- Run a full exit readiness assessment to identify your highest-value improvement opportunities
- Engage your CPA on entity structure and begin pre-sale tax planning
- Identify and begin working on your two or three lowest-scoring value drivers
- Implement clean bookkeeping practices that will produce three years of clean financial history
18–36 Months Before Your Target Sale
The structural work is underway. This window is for executing improvements and beginning to build the financial track record that buyers will evaluate.
Priority actions:
- Execute your value driver improvement plan — recurring revenue, management depth, customer diversification
- Build and maintain clean monthly financial records
- Engage a business broker or exit planner for a market-based opinion of value
- Begin documenting processes and systems
12–18 Months Before Your Target Sale
Pre-market preparation begins. The business should be approaching deal-readiness, and the focus shifts to presentation, documentation, and advisor team selection.
Priority actions:
- Finalize your SDE/EBITDA recast with CPA involvement
- Complete legal review — lease assignability, license status, compliance audit
- Select your transaction team: broker, M&A attorney, CPA
- Prepare your Confidential Information Memorandum
6–12 Months Before Your Target Sale
You’re on the market or approaching market. Buyer conversations are happening. Due diligence is near.
Priority actions:
- Manage buyer conversations through your broker
- Prepare for due diligence — organize your documentation package
- Negotiate LOI terms with full understanding of deal structure implications
- Model after-tax proceeds for any offers received
At or After LOI
The transaction is in motion. Focus shifts to due diligence management and closing.
Priority actions:
- Respond promptly and completely to due diligence requests
- Monitor working capital through the closing period
- Work with your CPA and attorney on purchase price allocation
- Plan for post-closing tax obligations and wealth management
The Complete Resource Library
Every article in The Orchard’s exit readiness and valuation series, organized by topic:
Valuation Fundamentals
- What Is a Business Worth? The 4 Valuation Methods Explained
- EBITDA Multiples by Industry: What Buyers Are Actually Paying Right Now
- Why Your Asking Price and Your Business Value Are Two Different Numbers
- The Difference Between Enterprise Value and Equity Value (And Why It Matters at Closing)
Exit Readiness
- The 10 Factors Buyers Score Before They Make an Offer
- How to Run an Exit Readiness Assessment on Your Client’s Business
- Red Flags That Kill Deals Before the LOI: A Pre-Sale Checklist
- What “Deal-Ready” Actually Looks Like — And How Long It Takes to Get There
Financial Documentation
- The EBITDA Add-Backs Buyers Accept vs. The Ones That Blow Up Deals
- How to Build a Seller’s Discretionary Earnings (SDE) Statement That Holds Up Under Due Diligence
- 3 Years of Financials: What Buyers Read, What They Ignore, and What Scares Them
- Why Clean Books Are Worth More Than a Higher Multiple
Value Drivers and Value Killers
- The 7 Value Drivers That Push Your Multiple Above the Midpoint
- Owner Dependency: The Single Biggest Value Killer in Small Business Sales
- How Customer Concentration Tanks a Valuation (And How to Fix It Before You Sell)
- Recurring Revenue vs. Project Revenue: How Buyer Perception Changes the Math
Deal Structure
- How Deal Structure Affects the Real Price You Walk Away With
- Earnouts: When They Make Sense and When They’re a Red Flag
- Seller Financing as a Value Lever: How It Can Increase Your Sale Price
- Asset Sale vs. Stock Sale: The Tax Impact Nobody Talks About Early Enough
Advisor Strategy
- What CPAs Need to Know Before Their Client Decides to Sell
- How Exit Planners and Business Brokers Can Work Together (Without Stepping on Each Other)
- Building an Exit Planning Practice: The Referral Engine Between Advisors
Free Tools to Apply What You’ve Learned
Reading this guide is the start. The next step is applying the concepts to your specific business — with real numbers, not abstract frameworks.
We’ve built a suite of free financial tools specifically for business owners, brokers, and advisors navigating the exit process. No software to install. No email required to access most tools. Just the calculations you need, built on real transaction data and financial methodology.
Business Valuation Calculator — Get a data-driven estimate of your business’s current market value using the SDE/EBITDA multiple approach. The most common starting point for any exit conversation.
Business Financing Calculator — Model deal structure scenarios, seller note terms, and SBA financing combinations. See exactly how different structure choices affect your actual proceeds.
EBITDA Growth Calculator — Project how specific operational improvements — margin expansion, revenue growth, cost reduction — translate into valuation impact. Make your improvement roadmap tangible.
Margin Health Check — Benchmark your margin profile against industry standards. Identify where your profitability compares to what buyers expect to see.
Explore All 26 Free Business Calculators — The complete PeachBiz calculator suite covering valuation, financing, margins, growth projections, and more.
Frequently Asked Questions
How long does it take to sell a business?
For a well-prepared business, the active sale process — from listing to closing — typically takes 6–12 months. Add 12–36 months of pre-sale preparation for businesses that need to address significant value-building or documentation work. The sellers who close fastest and at the best prices are almost always the ones who started preparing 18–36 months before they wanted to close.
What is the most important thing to do before selling a business?
If we had to choose one: get your financial documentation clean, accurate, and professionally reviewed. Clean, verifiable financials are the foundation of every other element of a successful sale — your valuation, your asking price, your buyer pool, your due diligence experience, and your final proceeds all depend on buyers and their lenders being able to trust your numbers.
How do I know what my business is worth?
Start with a normalized earnings calculation — your SDE or EBITDA after legitimate add-backs — and apply the appropriate industry multiple range. Use our free Business Valuation Calculator to get a data-driven estimate based on real transaction data. Then understand that your position within the industry range is determined by your specific value driver profile — which is exactly what Part 4 of this guide covers.
Do I need a business broker to sell my business?
For most small to mid-market businesses, yes. Business brokers provide market access, buyer qualification, deal management expertise, and negotiating experience that most business owners don’t have and can’t efficiently develop. The broker commission — typically 8–12% for Main Street deals — is almost always recouped through better offer terms and higher prices achieved through professional representation. The exception: larger deals where the seller has significant deal experience or where a known buyer is already in the picture.
What’s the difference between exit planning and business brokerage?
Exit planning is the long-horizon work of building a business into something worth selling — improving value drivers, cleaning up financials, reducing owner dependence, and preparing the owner emotionally and financially for the transition. Business brokerage is the transaction execution — taking a market-ready business to buyers and managing the sale process through closing. The best exits engage both: exit planning well in advance, brokerage when the business is ready to sell. See How Exit Planners and Business Brokers Can Work Together for the complete picture.
How do taxes affect my sale proceeds?
Significantly — and the tax impact depends heavily on how the deal is structured. Asset sales and stock sales are taxed very differently. Installment sale treatment can spread gain recognition across multiple years. Entity structure (C-Corp, S-Corp, LLC) dramatically affects the tax burden. The most important action: engage your CPA for pre-sale tax planning at least 12–24 months before your target sale date. See Asset Sale vs. Stock Sale: The Tax Impact Nobody Talks About Early Enough for a complete breakdown.
The Bottom Line
Selling a business well is not an accident. It’s the result of deliberate preparation — understanding what your business is worth, knowing what buyers are looking for, presenting your financials credibly, building the characteristics that command premium multiples, structuring the deal to maximize what you actually receive, and surrounding yourself with the right advisors who know their roles and work together effectively.
None of this is beyond the reach of any business owner willing to start the work early enough. The owners who achieve the best exits aren’t necessarily the ones with the best businesses. They’re the ones who understood the process, prepared systematically, and showed up to market with a business that was genuinely ready to sell.
That’s what The Orchard is here to help you do — one article, one tool, one conversation at a time.
Start where you are. Use what you know. Take the next step.
👉 Begin with your valuation baseline — free, no email required: Business Valuation Calculator
👉 Explore all free PeachBiz tools for business owners, brokers, and advisors: Business Calculators