Seller Financing as a Value Lever: How It Can Increase Your Sale Price
Most business owners think of financing as the buyer’s problem.
The buyer needs to figure out how to fund the acquisition — through savings, an SBA loan, private equity, or some combination. The seller’s job is to pick the best offer and close. Financing is a buyer concern, not a seller strategy.
That’s exactly backwards from how the most successful sellers approach it.
Strategic seller financing — deliberately offering to finance a portion of your deal — is one of the most powerful and underutilized tools available to sellers. Used correctly, it expands your buyer pool, accelerates your sale timeline, reduces the negotiating advantage buyers have in all-cash offers, and in most cases actually increases the price you receive — not just the total proceeds, but the enterprise value itself.
This article explains the mechanics: how seller financing works as a value lever, when offering it makes strategic sense, how to structure it to protect your interests, and how to use it to your advantage rather than simply accepting whatever a buyer’s deal team proposes.
The Counterintuitive Economics of Seller Financing
Here’s the fundamental insight that makes seller financing work as a value lever — and why most sellers miss it:
Offering seller financing doesn’t reduce the price you get. It increases it.
Let’s walk through why.
When you list your business for sale, the universe of qualified buyers is defined by who can fund the acquisition. If your business is priced at $1.5M and requires all-cash, your buyer pool consists of buyers who have $1.5M in readily available capital — plus what they need for working capital, transition costs, and reserves. That’s a small pool.
If your business is priced at $1.5M with 20% seller financing ($300,000 seller note), your buyer pool expands to include everyone who can bring $1.2M to the table — a substantially larger group. More qualified buyers competing for your business creates the conditions for better offers, less buyer leverage, and faster closing.
More buyers competing for the same business pushes the price up. It reduces the concessions buyers can demand. It shortens the time on market. And it gives you negotiating power you wouldn’t have with a single interested buyer.
The premium buyers pay for financing flexibility:
Sellers who offer financing proactively — as a feature of their listing rather than a concession in negotiations — consistently achieve 10–20% higher enterprise values than comparable businesses sold on an all-cash basis, according to broker transaction data.
The logic: buyers who need financing are willing to pay more for a business that comes with its own financing solution than they’d pay for one they have to fund entirely through third-party sources. The convenience, the cost savings (seller notes often carry lower interest rates than SBA loans), and the signal of seller confidence all justify a premium.
Why Seller Financing Signals Confidence — and Why Buyers Pay for It
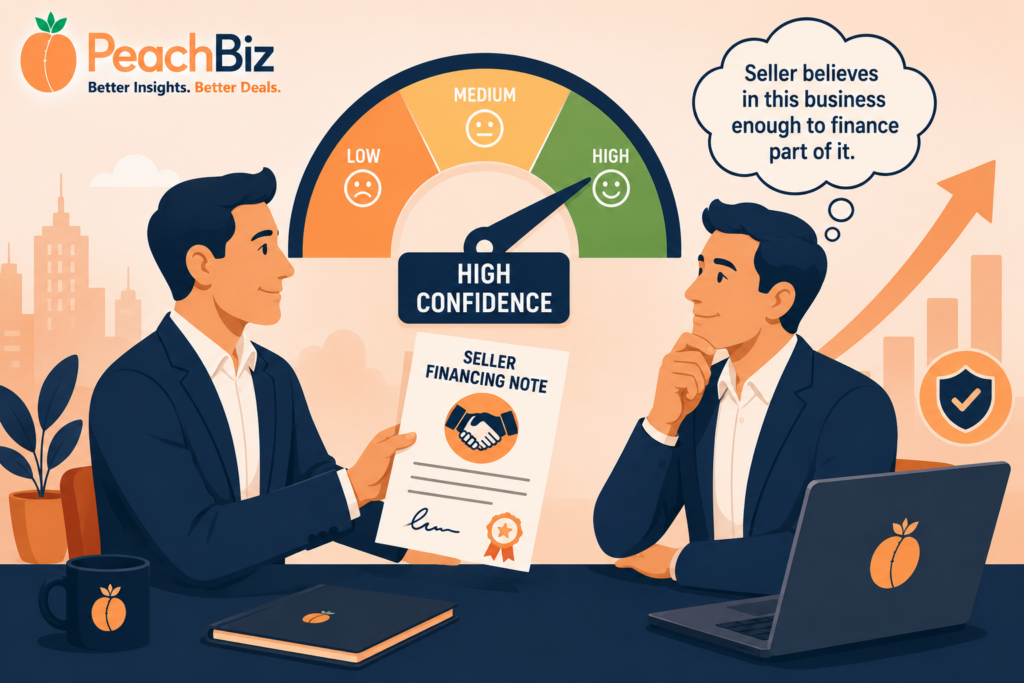
There’s a powerful psychological dimension to seller financing that translates directly into valuation.
When a seller offers financing, they’re implicitly stating: “I am confident enough in this business’s continued performance that I’m willing to accept payment over time rather than all at once.” That signal — that the seller has skin in the game through the seller note — is one of the strongest possible endorsements of the business’s earning power.
Buyers and their advisors know this. A seller who demands all cash is getting out as quickly as possible. A seller who accepts a note is expressing confidence that the business will continue to generate the cash flow needed to service that note. Buyers pay for that confidence because it reduces their risk assessment.
The SBA dimension:
In SBA-financed transactions, lenders often view seller notes favorably. A seller note demonstrates that the seller has enough confidence in the business to leave capital at risk — which makes the lender’s own position feel more secure. Some SBA lenders require a seller note specifically for this reason: it creates an alignment of interests between seller and buyer that pure all-cash deals don’t provide.
For sellers whose businesses are borderline for SBA approval — perhaps because of limited operating history, or a business in a cyclical sector — a voluntary seller note can be the difference between the buyer getting financing and the deal falling apart.
The Three Strategic Uses of Seller Financing
Seller financing isn’t one-size-fits-all. Here are the three specific situations where it works most powerfully as a value lever — and how to deploy it in each.
Strategy 1: The Premium Price Offer
The most direct use of seller financing as a value lever is to proactively offer it as a feature that justifies a higher asking price.
How it works:
Rather than listing at $1.5M all-cash and waiting to see if buyers propose seller financing as a concession, you list at $1.65M with 15% seller financing ($247,500 seller note at 6.5% over 5 years) as an explicitly offered feature of the deal.
The higher asking price is justifiable because:
- The financing option expands the buyer pool, creating more competition
- Buyers who access financing through your note save on loan origination fees, underwriting time, and potentially interest rates compared to third-party financing
- The seller’s willingness to finance signals confidence that commands a premium
What you need to protect your position:
- A solid buyer with demonstrated operational capability
- A business with strong, documented cash flows that can comfortably service the note
- Appropriate security (UCC lien on business assets, possibly a personal guarantee from the buyer)
- Clear note terms documented in the purchase agreement
The math:
All-cash offer accepted: $1,500,000 at closing (minus costs)
Seller financed deal:
- Enterprise value: $1,650,000
- Cash at closing: $1,402,500 (85%)
- Seller note: $247,500 at 6.5% over 5 years = $57,700 in total interest
- Total proceeds: ~$1,707,700 over 5 years
You receive slightly less at closing but $207,700 more in total proceeds. And because the higher price attracted more buyers and created competition, you likely got better terms on the cash portion as well.
Strategy 2: The Expanded Buyer Pool Play
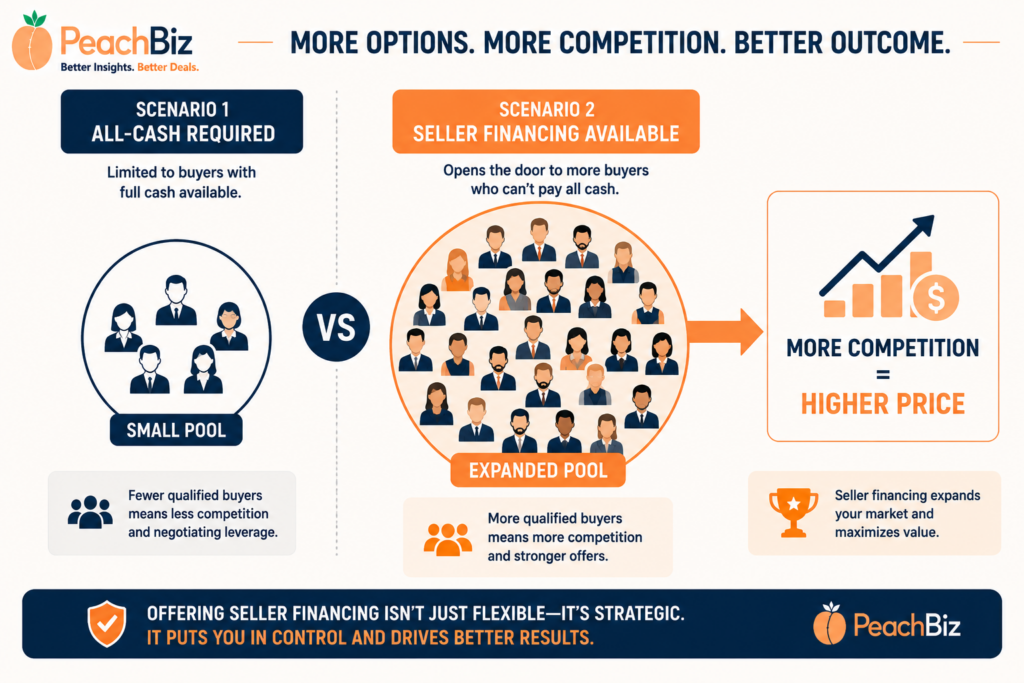
Sometimes the strategic value of seller financing isn’t about getting a higher price from the same buyer pool — it’s about accessing a completely different buyer pool that wouldn’t otherwise be able to acquire your business.
This strategy is most relevant for:
Businesses in the $500K–$2M range where all-cash buyers are rare. At these price points, most qualified buyers need some combination of SBA financing and seller financing to close the deal. A seller who refuses any financing is effectively limiting themselves to an extremely small pool of cash-rich buyers who have less incentive to pay a premium because they have many options.
Businesses that don’t qualify for full SBA financing. Some businesses — those with limited operating history, inconsistent financials, certain industry classifications, or concentration risk — face challenges accessing full SBA financing. A seller who supplements the buyer’s financing with a seller note can bridge a gap that makes the deal possible when it otherwise wouldn’t be.
Businesses with a specific ideal buyer in mind. If you want to sell to a management team member, a key employee, or a family successor who has operational capability but limited capital, seller financing may be the only way to make the transaction work. These buyers often pay a relationship premium — they know the business, they’re committed to its legacy, and they have lower transition risk — that makes the financing worthwhile.
Implementation:
When expanding the buyer pool is the goal, seller financing should be prominently featured in your listing materials — not buried in deal terms. “Seller financing available to qualified buyers” in the listing headline directly attracts a segment of the buyer market that filters out non-financing businesses before they even look at the details.
Strategy 3: The Negotiating Chip
The third strategic use of seller financing is as a deliberate negotiating chip — something you’re prepared to offer, but only in exchange for concessions on other deal terms.
This approach works best when you have a buyer who is close to their financing ceiling and needs a small seller note to make the deal work, but who is also pushing you on price or terms elsewhere.
How to deploy it:
Rather than proactively offering financing, hold it in reserve. If a buyer pushes for a price reduction, a larger earnout, or other unfavorable terms, introduce seller financing as a counter: “I’m not willing to reduce the price by $150,000, but I am willing to offer a seller note for $150,000 at 6% over four years if we can close at the asking price.”
In this scenario, you’ve maintained the enterprise value while using your willingness to finance as the concession — rather than giving up cash value. The buyer gets the deal structure flexibility they needed. You get the price you wanted.
This works because seller financing and price concessions are different currencies. A $150,000 seller note costs you $150,000 in day-one cash but returns $175,000 over the note term with interest. A $150,000 price reduction costs you $150,000 with no return. From the buyer’s perspective, both solve their financing gap. From yours, the seller note is clearly better.
Structuring Seller Financing to Protect Yourself
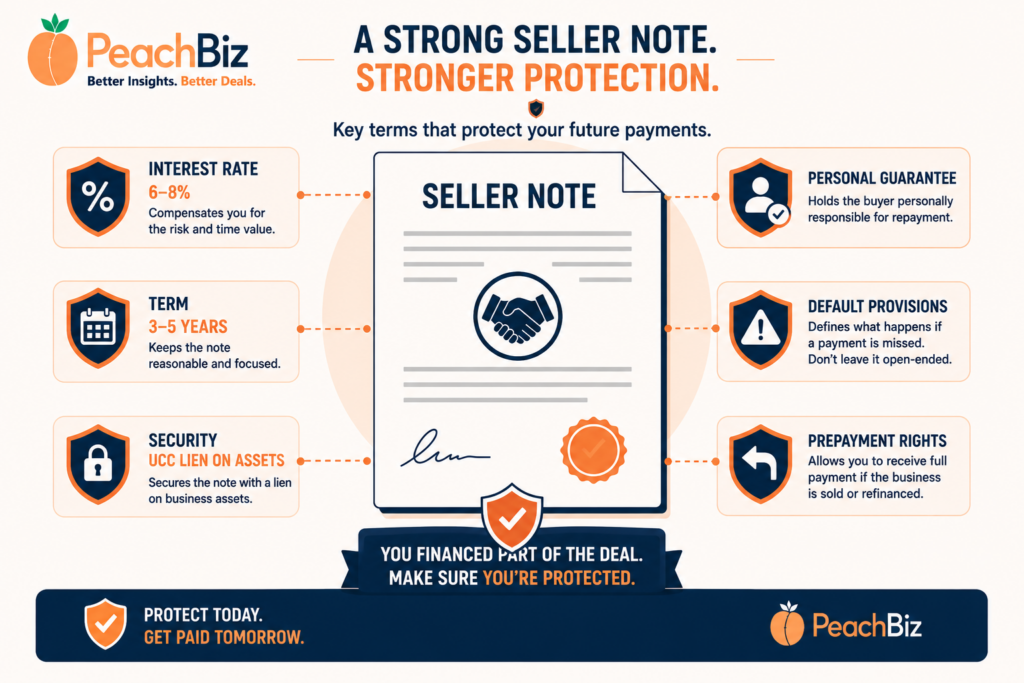
Offering seller financing strategically doesn’t mean offering it carelessly. The terms you negotiate and the protections you put in place are what separate a well-structured seller note from an exposed position.
Interest Rate
Seller notes should carry a market-rate interest return — not zero percent, which provides no compensation for the time value of money and the risk of the deferred payment. Current market rates for seller notes typically run 6–8%. This rate should be clearly documented and consistent with the prevailing rate for the risk profile of the note.
Term Length
The shorter the term, the better from a seller’s perspective. Three to five years is the standard range. Longer terms increase your exposure to buyer performance risk and reduce the present value of your total proceeds. Resist requests for seven or ten-year terms unless accompanied by significantly higher interest rates or other compensating terms.
Security — UCC Lien on Business Assets
Your seller note should be secured by the business assets through a UCC-1 financing statement filed with the state. This gives you a perfected security interest in the business — meaning if the buyer defaults, you have legal rights to the collateral (the business assets) rather than just an unsecured claim against the buyer.
In SBA-financed deals, be aware that your seller note will typically be subordinated to the SBA loan — meaning the SBA lender has a senior claim on the collateral ahead of you in a default scenario. This is standard and usually unavoidable in SBA transactions, but it’s important to understand the priority structure before you agree to the note amount.
Personal Guarantee
If the buyer is a business entity (LLC, corporation), negotiate for a personal guarantee from the individual buyer. This means you can pursue the buyer personally — not just the business entity — if they default on the note. Personal guarantees are not always achievable (PE buyers will typically refuse them), but for individual buyers they’re a reasonable and commonly accepted protection.
Default Provisions
Your note should specify what constitutes a default (missed payment, late payment beyond a cure period, bankruptcy filing) and what remedies you have upon default. Default remedies typically include acceleration of the remaining balance (the full note becomes immediately due) and enforcement of your security interest.
Prepayment Rights
Include language allowing the buyer to prepay the note without penalty. This is seller-friendly: if the buyer is doing well, early payoff of the note reduces your exposure. Some sellers also negotiate a prepayment discount — accepting slightly less than the full remaining balance in exchange for early payoff — which can be worth it for the certainty and immediacy of the payment.
Standstill and Subordination in SBA Deals
If SBA financing is involved, understand that the SBA will almost certainly require your seller note to include a standstill provision — a period (typically 24 months after closing) during which you cannot receive principal payments on the note. You can receive interest payments during the standstill, but principal repayment is deferred. This is standard and not negotiable in SBA transactions — but it’s important to factor into your cash flow planning.
When Seller Financing Is NOT the Right Move
Strategic seller financing makes sense in specific situations. In others, it introduces risk without sufficient compensating benefit.
Don’t offer seller financing when:
You need the full proceeds immediately. If your retirement plan, debt payoff obligations, or next investment requires full proceeds at closing, a seller note creates a cash flow gap that the interest income doesn’t compensate for. Know your financial needs before you offer any deferred payment structure.
The buyer’s creditworthiness is questionable. A seller note is a loan to your buyer. If you have meaningful concerns about their operational capability, financial stability, or personal financial position — regardless of how well they presented in meetings — those concerns should make you skeptical of any structure where you’re a creditor to them post-closing.
The business has thin margins that make note service risky. A buyer who is servicing an SBA loan, a seller note, and trying to build the business simultaneously needs sufficient cash flow to do all three. If your business operates on thin margins and the combined debt service would be stressful for a new owner, the note increases the risk of default rather than reducing it. Model the debt service coverage before you offer financing.
The business is in a declining industry or has declining performance. Seller financing on a business with deteriorating performance is a bet that the buyer can reverse the trend. If you’re not confident in that outcome, a seller note exposes you to the downside.
Seller Financing and Your Tax Position
One often-overlooked advantage of seller financing is the installment sale tax treatment it enables.
Under IRC Section 453, when a seller receives payments over time rather than all at once, the gain is recognized proportionally as payments are received — rather than entirely in the year of sale. This means:
- Your taxable gain is spread across the note term rather than recognized in a single year
- You defer a portion of your tax liability, keeping more capital working for you in the short term
- In some scenarios, installment sale treatment can keep you in a lower tax bracket than an all-cash sale would
The tax benefit is real and can be meaningful — particularly for sellers with large capital gains who would otherwise be pushed into the highest capital gains bracket in the year of sale.
Your CPA should model the after-tax impact of installment sale treatment as part of your deal structure analysis. In some cases, the tax deferral benefit alone justifies accepting a seller note that you might otherwise decline.
We cover sale structure tax implications in full in Asset Sale vs. Stock Sale: The Tax Impact Nobody Talks About Early Enough.
👉 Use our free Business Financing Calculator to model seller note scenarios — including total return calculations, monthly payment projections, and the impact of different interest rates and terms on your proceeds.
Frequently Asked Questions
How much seller financing is typical in a small business sale?
The most common seller note in SBA-financed transactions is 10% of the purchase price, required by the SBA as a standby note. In non-SBA transactions, seller financing ranges from 10–30% depending on the deal dynamics. Notes above 30% of enterprise value are uncommon and typically signal a buyer with insufficient capital or a business with financing challenges — both of which warrant careful evaluation.
Can I offer seller financing and still get a good price?
Yes — and as this article explains, offering seller financing strategically can actually increase the price you receive relative to a comparable all-cash listing. The key is positioning it as a feature rather than a concession, using it to attract more buyers and create competitive pressure, and ensuring the terms adequately compensate you for the deferred payment.
What interest rate should I charge on a seller note?
Market rates for seller notes currently run 6–8%. Rates below the Applicable Federal Rate (AFR) published by the IRS each month may result in imputed interest — the IRS can treat below-market loans as having a higher effective interest rate regardless of what the note says. Your CPA can advise on the current AFR and the minimum rate required to avoid imputed interest issues.
What happens to my seller note if the buyer sells the business?
Your note should include a due-on-sale provision — a clause that makes the full remaining balance of the note immediately due and payable if the buyer sells or transfers the business. Without this provision, your note obligation could pass to a new owner you have no relationship with and no ability to evaluate. Due-on-sale protection is a standard and important provision in any seller note.
Is seller financing more common in certain industries?
Yes — seller financing is most common in industries where all-cash buyers are rare (service businesses, retail, restaurants), in transactions where SBA financing is the primary vehicle (which typically requires a seller note), and in seller-to-management or family succession transactions where the buyer has strong operational capability but limited capital. It’s less common in larger transactions where institutional buyers typically have ample capital resources.
The Bottom Line
Seller financing isn’t a concession you make when a buyer can’t afford your price. Used strategically, it’s a tool you deploy to command a higher price, attract more buyers, accelerate your timeline, and create negotiating leverage you wouldn’t otherwise have.
The sellers who use it most effectively treat it as a feature — something they’ve decided to offer because it serves their interests — not as a fallback when an all-cash deal doesn’t materialize. They structure it carefully, protect themselves appropriately, and use the tax and competitive advantages it creates.
The bottom line: if your business is well-suited for seller financing and your financial situation allows you to defer a portion of your proceeds, offering it strategically is very likely to result in more money at a better price than holding out for all-cash.
That’s the counterintuitive truth about seller financing. It’s not the seller’s concession. It’s the seller’s advantage.
👉 Model your seller financing scenarios with our free Business Financing Calculator — designed to show exactly how different note terms affect your total proceeds and annual cash flows.
Related Reading
- How Deal Structure Affects the Real Price You Walk Away With
- Earnouts: When They Make Sense and When They’re a Red Flag
- Asset Sale vs. Stock Sale: The Tax Impact Nobody Talks About Early Enough
- The Difference Between Enterprise Value and Equity Value (And Why It Matters at Closing)
- What Is a Business Worth? The 4 Valuation Methods Explained
- EBITDA Multiples by Industry: What Buyers Are Actually Paying Right Now
- Explore All Free PeachBiz Business Calculators