What CPAs Need to Know Before Their Client Decides to Sell
It happens in every CPA’s practice. A long-term client — someone you’ve worked with for eight, twelve, fifteen years — calls and says: “I’ve been thinking about selling the business. I want to talk through what that looks like.”
And right there, in that moment, your response determines whether you remain at the center of your client’s most significant financial event — or whether you get sidelined while a business broker, an M&A attorney, and a financial advisor you’ve never met make decisions that affect your client’s financial life for the next twenty years.
Most CPAs aren’t trained in M&A. Accounting programs teach financial statements, tax law, and audit methodology — not deal structure, SDE normalization, purchase price allocation negotiations, or earnout tax treatment. And yet the moment a client decides to sell, all of those things become critically important — and the CPA is often the first advisor they call.
This article is for the CPA who wants to be genuinely useful in that conversation — not just a passive observer or a late-stage tax preparer, but a proactive, knowledgeable advisor who helps their client achieve the best possible outcome from the most significant financial transaction of their business life.
Here’s what you need to know before that call comes.
Why CPAs Are the Most Important Advisor in an Exit — And Why Most Don’t Know It
The CPA’s position in the exit planning ecosystem is unique and underappreciated.
You know things no other advisor knows. You know the client’s true financial picture — not the curated version they show brokers, but the reality of how the business has been run, what’s been expensed personally, where the books are weak, and what the tax return doesn’t say that it should. You know the client’s personal financial situation — their retirement needs, their other assets, their family dynamics, their timeline pressures.
You’re also the most trusted financial advisor most business owners have. When they receive an offer that confuses them, they call you. When their attorney explains something they don’t understand, they call you to translate. When a buyer’s advisor challenges their financial presentation, they look to you to defend it.
And critically — you often know about the intention to sell before anyone else does. Which means you have the opportunity to shape the outcome before the process begins, rather than reacting to decisions already made.
That early position is worth an enormous amount to your client — and to your practice relationship. CPAs who engage deeply in exit planning don’t just help their clients better. They cement their own indispensability in the client relationship and in the eventual transaction.
The knowledge gap that most CPAs carry into these conversations isn’t a reflection of their capability — it’s a reflection of how accounting training is structured. This article fills the most critical parts of that gap.
The First Conversation: What to Ask and What to Listen For
When a client tells you they’re thinking about selling, the instinct is to immediately start thinking about taxes. That’s correct — but premature. Before the tax conversation, you need to understand the situation clearly.
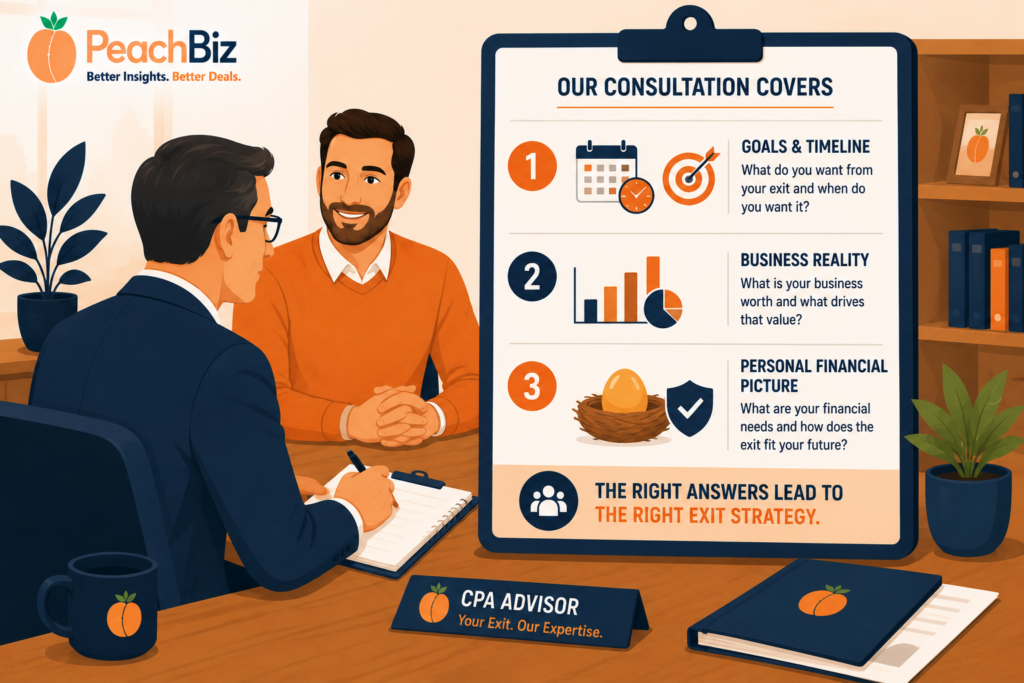
On goals and timeline:
- What does a successful exit look like to you — maximum price, fastest close, right buyer, legacy preservation, or some combination?
- When are you hoping to close — and is that a fixed deadline or a preference?
- Do you have a specific number in mind? Where did that number come from?
- What does your life look like after the sale — retirement, a new venture, travel?
On the business:
- Have you had any preliminary conversations with brokers or buyers — even informal ones?
- Do you have any existing offers, letters of intent, or expressions of interest?
- Who else knows about this — key employees, family members, business partners?
- Are there any current legal issues, regulatory matters, or business disputes I should know about?
- Is there a partner or co-owner whose buy-in is needed?
On the personal financial picture:
- What do you need from the sale proceeds to fund your next chapter — and have you modeled that?
- What are your current personal liabilities that might affect the net proceeds you need?
- Do you have other significant assets or income sources beyond this business?
- Have you thought about estate planning implications of a large liquidity event?
The answers to these questions tell you what kind of exit planning engagement you’re walking into — whether this is a long-runway situation where you have time to optimize, a compressed timeline where damage control is the priority, or something in between.
They also tell you what the client doesn’t know — which gaps in their understanding need to be filled before they make decisions they can’t reverse.
The Tax Planning Priorities: What Needs to Happen Before the LOI
Once you understand the situation, the tax planning work begins. Here’s the sequence of priorities — ordered by what has the most impact and what needs the most lead time.
Priority 1: Entity Structure Review
The single highest-impact pre-sale tax planning decision — and the one requiring the most lead time — is entity structure.
A C-Corporation client facing an asset sale faces double taxation: corporate-level tax on the gain plus shareholder-level tax on the distribution. Depending on state taxes, this can consume 40–55% of gross proceeds. A comparable S-Corp or LLC client in the same asset sale pays substantially less.
If your client is a C-Corp, the first question is: should they convert to an S-Corp before the sale? The analysis involves:
- The built-in gains (BIG) tax under IRC Section 1374, which applies if an S-Corp election is made within 5 years of an asset sale. If the client has more than 5 years before their target sale date, conversion may eliminate the BIG tax exposure entirely.
- The cost of maintaining C-Corp status vs. the tax savings from conversion
- State tax implications of the conversion (some states don’t recognize S-Corp elections)
- The interaction with any existing C-Corp tax attributes (NOLs, credits) that might be affected by the election
If there isn’t time for a full S-Corp conversion, the 338(h)(10) election for S-Corp buyers offers a partial solution — but only if the buyer is also a C-Corp or S-Corp, and only if both parties agree to make the election. Understanding this option and when to propose it is valuable M&A knowledge for every CPA.
Timeline requirement: Entity structure decisions need to be made 1–5 years before the sale, not 60 days before closing. If a client comes to you with a fixed 12-month timeline and a C-Corp structure, your options are significantly more limited.
Priority 2: The Asset vs. Stock Sale Analysis
Every client selling a business needs a side-by-side tax projection for both asset sale and stock sale scenarios at their target enterprise value.
This projection — built with the client’s specific asset mix, tax basis, state tax rates, and income picture — quantifies what each structure actually costs in after-tax proceeds. It gives you and your client a clear, defensible number to use in deal structure negotiations.
The analysis should include:
- Federal and state tax on each asset class in an asset sale (receivables, inventory, equipment recapture, goodwill)
- Federal and state capital gains tax in a stock sale
- Net after-tax proceeds in each scenario
- The price premium the client needs to demand in an asset sale to be indifferent to a stock sale
That last number is the most practically useful output: if a stock sale nets your client $1.55M after taxes and an asset sale at the same enterprise value nets $1.46M, the client needs $90,000+ in additional enterprise value to be indifferent to the asset sale. That’s a specific, defensible negotiating position — and you’ve given your client the ability to make it.
Priority 3: Installment Sale Modeling
For clients who will accept any form of deferred payment — seller notes, earnouts, equity rollovers — installment sale treatment under IRC Section 453 can spread the gain recognition and potentially reduce the effective tax rate by keeping the client in a lower bracket across multiple years.
Model the installment sale outcome for any deal structure that includes deferred payments. Compare it to the full recognition option. In some cases, the tax deferral from installment treatment is worth more than a higher interest rate on the seller note — which changes the negotiating calculus around note terms.
Key installment sale issues to address:
- Dealer property exclusions (most business assets qualify for installment treatment, but some don’t)
- Contingent payment sales (earnouts with uncertain total amounts have specific installment sale rules under Reg. 15a.453-1)
- The interest charge on deferred gains above $5M (IRC Section 453A)
- State conformity with federal installment sale treatment (some states require full gain recognition in the year of sale regardless of federal treatment)
Priority 4: Qualified Small Business Stock (QSBS) Analysis
For C-Corp clients whose shares qualify as Qualified Small Business Stock under IRC Section 1202, the tax implications of a sale are dramatically different — potentially including a complete federal exclusion of capital gains on the sale of qualifying shares (up to $10M or 10x basis, whichever is greater).
QSBS qualification requirements include:
- The business must be a C-Corp (not S-Corp, LLC, or partnership)
- The business must be an active trade or business, not a holding company or certain excluded industries (services businesses in health, law, finance, etc. are excluded)
- The stock must have been acquired at original issuance (not purchased from another shareholder)
- The stock must have been held for more than 5 years
- Gross assets of the corporation must not exceed $50M at time of issuance
If your C-Corp client qualifies — and they won’t know unless you check — this exclusion can be the most valuable tax planning opportunity of their financial life. Check before you recommend S-Corp conversion.
Priority 5: Estate Planning Integration
A large liquidity event doesn’t just affect income taxes — it affects the client’s estate. For clients with significant estate planning concerns, the timing and structure of a business sale interact with:
- Gift tax annual exclusions and lifetime exemption usage
- Charitable giving strategies (Charitable Remainder Trusts, Donor Advised Funds, Qualified Opportunity Zone investments post-sale)
- Trust structures that might receive sale proceeds for estate tax efficiency
- The step-up in basis at death and how it interacts with installment sale treatment
Estate planning decisions often need to be made before the sale closes — sometimes before the LOI is signed. Coordinate with the client’s estate attorney early.
The Financial Documentation Role: Where CPAs Add Immediate Value
Beyond tax planning, CPAs play a critical role in preparing the financial documentation that buyers and their advisors will scrutinize during due diligence. This is where your technical skills are most directly deployable in the sale process.
The SDE/EBITDA Recast
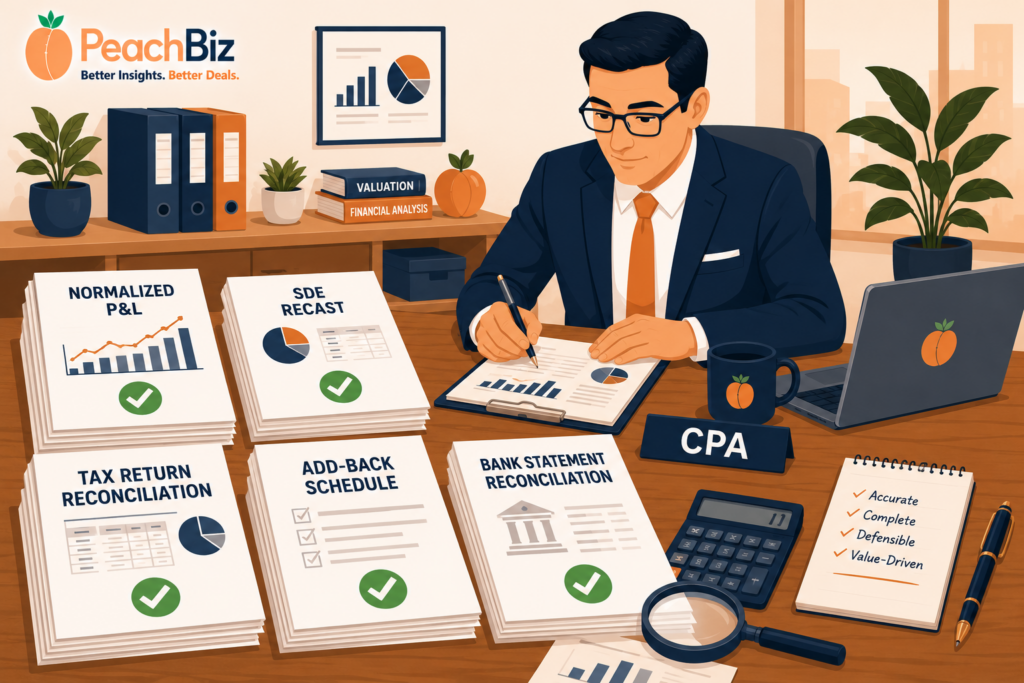
The normalized earnings statement — showing the business’s true economic output after add-backs — is the foundation of the valuation. As the CPA, you’re uniquely positioned to build this document credibly because you have access to the tax returns, payroll records, and underlying financial data that every add-back must be traced back to.
Your involvement in the SDE recast adds enormous credibility to the financial presentation. A buyer’s advisor who sees “Recast prepared by [CPA firm], reconciled to federal tax returns” is significantly more likely to accept the add-backs without challenge than one who sees a seller-prepared spreadsheet with no professional review.
Build the recast from the tax return — not from internal P&Ls — and document every add-back with the specific source document. Three years, side by side, with a Notes column on every line.
Tax Return to P&L Reconciliation
One of the first things sophisticated buyers do is compare your client’s tax returns to their P&L statements. Unexplained differences — even legitimate ones from accounting method differences — create questions that slow the process and erode confidence.
Prepare a clear reconciliation document that bridges the tax return to the management P&L for each of the three presentation years. Explain every significant difference. This document, prepared by you and available in the due diligence package from day one, removes one of the most common early-stage buyer concerns.
Quality of Earnings Assessment
For larger transactions ($2M+ enterprise value), buyers often commission a Quality of Earnings (QoE) report from an independent accounting firm. This is a detailed analysis of the sustainability, accuracy, and quality of the seller’s reported earnings — essentially a deep audit of the SDE recast.
If your client is in this range, prepare them for the QoE process. Help them understand what will be reviewed, identify any areas where the analysis might surface questions, and ensure the financial presentation is as clean as possible before the buyer’s QoE team arrives.
The Advisor Team: Your Role and Everyone Else’s
One of the most common mistakes CPAs make in a client’s exit is trying to handle too much — and one of the second most common is not handling enough. Understanding where your expertise adds the most value and where other specialists are needed is essential for serving your client well.
Your role (CPA):
- Pre-sale tax planning and structure optimization
- SDE/EBITDA recast preparation and verification
- Tax return to P&L reconciliation
- Installment sale and deal structure tax modeling
- Purchase price allocation review and negotiation
- Post-closing tax return preparation
Business broker’s role:
- Business valuation and market pricing
- Marketing the business to qualified buyers
- Managing the sale process and buyer communications
- Negotiating deal terms and LOI
- Coordinating due diligence
M&A attorney’s role:
- Drafting and negotiating the purchase agreement
- Managing legal due diligence
- Addressing representations, warranties, and indemnification
- Structuring the closing and handling the legal transfer
Financial planner/wealth advisor’s role:
- Post-sale investment strategy for proceeds
- Retirement income planning
- Insurance and risk management after the sale
- Charitable giving and philanthropic planning
The mistake CPAs most often make is attempting to fill the broker or attorney role — giving valuation opinions they’re not positioned to defend or negotiating deal terms outside their expertise. The mistake they make second most often is staying too narrowly in the tax lane and missing opportunities to add value in the financial documentation and due diligence support role where their skills are directly applicable.
Know your lane. And help your client understand that they need a full team, not just a CPA who’s read a few M&A articles.
The Due Diligence Phase: What to Expect and How to Help
When due diligence begins — typically after the LOI is signed — you’ll be called on to respond to financial requests from the buyer’s team. Here’s what to expect and how to be most useful.
What buyers typically request:
- Three years of federal business tax returns (the buyer will independently request transcripts from the IRS via Form 4506-C)
- Three to five years of monthly P&L statements and balance sheets
- Detailed general ledger or trial balance for the most recent fiscal year
- Payroll records supporting the owner compensation add-back
- Depreciation schedules
- Bank statements reconciled to monthly revenue
- Accounts receivable and accounts payable aging reports
- Documentation for any significant add-backs
How to be most useful:
Organize the financial documentation package proactively — before the buyer asks for it. A well-organized due diligence package that anticipates the buyer’s requests shortens the due diligence timeline, reduces back-and-forth, and signals that the business is professionally managed.
Be available to respond to follow-up questions from the buyer’s CPA or financial advisor. These conversations — which can include detailed questions about specific line items, unusual expense categories, or year-over-year variances — are where your knowledge of the client’s financial history is most directly valuable.
If the buyer engages a Quality of Earnings firm, position yourself as a cooperative resource rather than an adversary. The QoE team is doing their job; making that process efficient serves your client.
The purchase price allocation negotiation:
Once the deal structure is established, the purchase price allocation across IRS asset classes becomes a negotiation. Buyers want more allocated to depreciable assets (faster tax benefit). Sellers want more allocated to goodwill (capital gains treatment). Your role is to advocate for your client’s interest in this allocation while ensuring the final allocation is defensible and consistent with the actual fair market values of the assets.
This is one of the most direct and concrete ways you add value in the transaction — and one of the places where CPA involvement most directly affects after-tax proceeds.
Building Your Exit Planning Practice
For CPAs who want to develop deeper expertise in this area, the exit planning market represents a significant and growing opportunity. Here’s how to position yourself:
Build your M&A knowledge systematically. The AICPA’s Certified in Financial Forensics (CFF) credential covers some transaction-related accounting. The Exit Planning Institute’s Certified Exit Planning Advisor (CEPA) designation specifically targets the exit planning market and provides a structured curriculum. BVR (Business Valuation Resources) and other professional education providers offer transaction-specific courses.
Build relationships with transaction specialists. The most effective CPAs in the exit planning space have strong working relationships with business brokers, M&A attorneys, and financial planners who serve the same client demographic. These relationships generate referrals in both directions — you refer clients who need their services, they refer clients who need yours.
Create a standard exit planning engagement. Rather than approaching every exit planning situation ad hoc, develop a standard engagement offering — an exit readiness review that includes entity structure analysis, three-year financial normalization, and tax structure comparison — that you can offer proactively to clients who are 2–5 years from their target exit date. This proactive offering positions you ahead of the process rather than reactive to it.
Communicate proactively with clients about exit timing. Many clients who are planning exits aren’t discussing them with their CPA until it’s too late to optimize. Build a regular touchpoint into your client relationships — an annual question about long-term business plans — that surfaces exit intentions early enough to act on them.
👉 Familiarize yourself with the tools your clients will be using in the exit process. Our free Business Valuation Calculator gives clients a market-based baseline that you can use as a starting point for tax projection modeling.
👉 Use our EBITDA Growth Calculator with clients to model how operational improvements in the 12–24 months before sale translate into valuation impact — a powerful tool for making your pre-sale advisory work tangible.
Frequently Asked Questions
When should a CPA start working on exit planning with a client?
Ideally 2–5 years before the client’s target sale date. This window allows time for entity structure decisions (including S-Corp conversions that require 5+ years to avoid BIG tax), financial documentation cleanup, operational improvements that affect valuation, and proactive tax planning. One to two years is workable for the tax planning elements but limits structural options. Six months or less is largely reactive — damage control rather than optimization.
Should CPAs provide business valuations for sale purposes?
Most CPAs are not qualified business valuators and should not provide formal valuations for sale purposes. If a formal valuation is needed — for estate planning, partnership dissolution, or litigation — refer to a Certified Valuation Analyst (CVA) or Accredited in Business Valuation (ABV) professional. CPAs can and should build SDE/EBITDA recasts and provide tax projections based on assumed enterprise values — that’s accounting work, not valuation work. The distinction matters both professionally and for the client’s protection.
What is a Quality of Earnings report and should CPAs prepare them?
A Quality of Earnings (QoE) report is an independent analysis of the sustainability and accuracy of a business’s reported earnings, typically commissioned by the buyer. It’s usually prepared by a transaction advisory team at an accounting firm with specific M&A experience. Your client’s CPA should not prepare the QoE — that would be the CPA auditing their own work, which creates independence issues. Your role is to cooperate with and facilitate the buyer’s QoE process, not to perform it.
How does a business sale affect the client’s personal tax return?
Significantly. The gain from a business sale — particularly a large one — is typically recognized in a single tax year, potentially pushing the client into the highest capital gains bracket, triggering Net Investment Income Tax (NIIT) under IRC Section 1411, affecting state tax obligations across multiple jurisdictions, and potentially triggering alternative minimum tax considerations. Model the full personal tax picture for the year of sale before the deal closes, and plan accordingly — including estimated tax payments, installment sale elections, and any offsetting strategies.
What’s the CPA’s role after the sale closes?
Several important functions: preparing the final business tax return for the sold entity, preparing the client’s personal tax return for the year of sale (which includes reporting the sale and any installment sale elections), managing the purchase price allocation documentation for both the business return and personal return, advising on investment of proceeds from a tax perspective, and coordinating with the estate planning team on post-sale wealth management.
The Bottom Line
When a client says they’re thinking about selling, you have a narrow window to position yourself as an indispensable part of the exit team — or to become an afterthought while other advisors take the lead.
The CPAs who serve their clients best in exit situations are the ones who show up to that first conversation with a clear framework for what they need to understand, what needs to happen first, and what their specific role is in the process. They don’t try to be the broker or the attorney. They go deep in the areas where their expertise creates the most value — tax structure, financial documentation, and deal economics — and they build a team around the areas where it doesn’t.
The knowledge in this article is the starting point. The ongoing investment — in M&A education, in transaction relationships, in a structured exit planning practice — is what separates the CPAs who are called first from the ones who are called last.
Start that investment now. Your clients will benefit, and so will your practice.
👉 Explore the tools your clients will be using as they prepare for exit — starting with our free Business Valuation Calculator.
Related Reading
- How Exit Planners and Business Brokers Can Work Together (Without Stepping on Each Other)
- Building an Exit Planning Practice: The Referral Engine Between Advisors
- Asset Sale vs. Stock Sale: The Tax Impact Nobody Talks About Early Enough
- How to Run an Exit Readiness Assessment on Your Client’s Business
- The EBITDA Add-Backs Buyers Accept vs. The Ones That Blow Up Deals
- How to Build a Seller’s Discretionary Earnings (SDE) Statement That Holds Up Under Due Diligence
- Explore All Free PeachBiz Business Calculators